
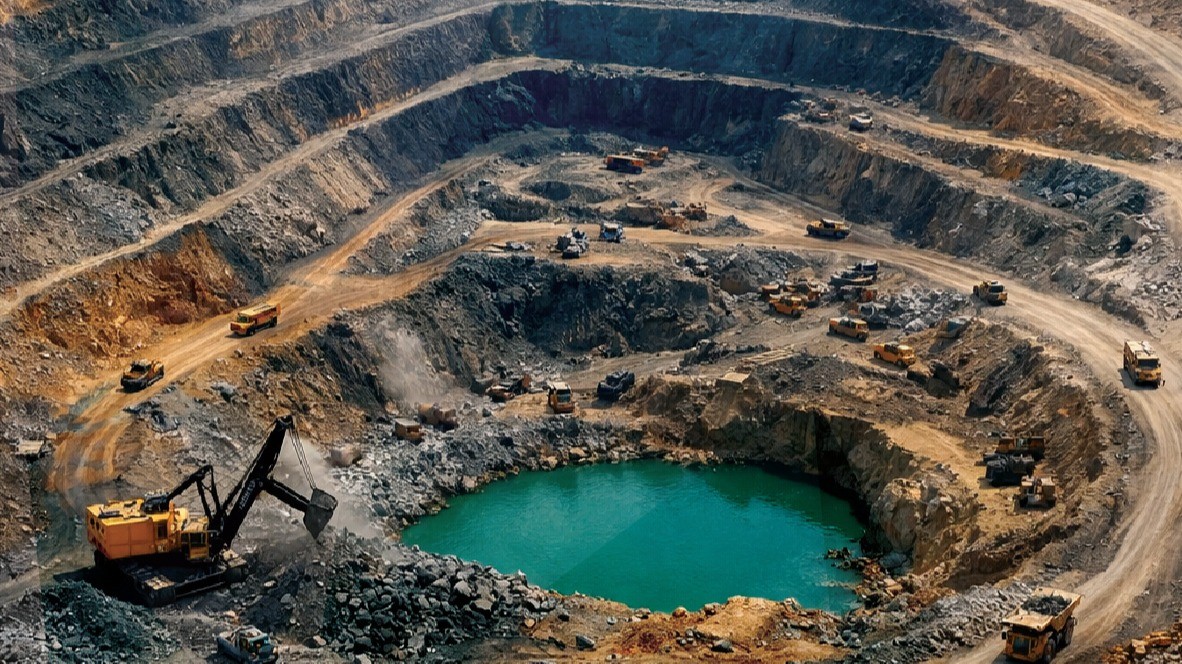
The extractive sector plays a dominant role in the economy of the Democratic Republic of the Congo (DRC), accounting for 55% of GDP and 48% of tax revenue in 2023. This makes effective fiscal analysis and revenue forecasting essential for credible public financial management.

How AI Is Rewriting the Rules of Finance — With Corporate Lessons from Africa
Artificial Intelligence is no longer a theoretical conversation in African boardrooms. It is operational. Across banking, fintech, telecoms, retail, and insurance, AI is reshaping how finance functions measure risk, allocate capital, detect fraud, and forecast growth.
Mergers and Acquisitions – Deal Structuring
The most basic definition of deal structuring in my opinion is “an agreement between ACQUIRER and TARGET where RIGHTS and OBLIGATIONS of the parties are defined.” These rights and obligations are allocated pertaining to three main components of the deal, namely: future cash flows, risk and value. For the parties involved in a deal to conclude on one, there is a pathway to be followed as depicted. [Insert chart here]. On the transaction pathway, we focus on evaluation and execution portions for this paper as highlighted in the chart. In deal structuring, our focal areas would be performing a high level financial analysis, doing a due diligence exercise and finally a buy-side valuation. In most instances, the seller would also have performed their own sell-side valuation in which case the buy-side valuation serves to confirm or disprove buy-side. Failure to perform these actions may lead to the deal failing to work. Reading from mergers and acquisitions (https://www.mergersandinquisitions.com/why-most-ma-deals-fail/) the following may be reasons why deals fail: A due diligence exercise is defined on Investopedia as “an investigation or audit of a potential investment or product to confirm all facts, such as reviewing all financial records, plus anything else deemed material.” Some of the pertinent business aspects to be considered in a due diligence exercise include: Once the acquirer is satisfied with the answers to the due diligence questions, they may proceed to perform a buy-side valuation. The valuation is critical to whether the deal occurs or not and is typically the instance where the deal is made or broken. Valuation may be either pre-money valuations or post-money valuations. Pre-money valuations do not factor the new capital injections while post-money valuations take into account the financial impact of the new capital injected. It is highly recommended that both the target and the acquirer engage corporate finance and legal specialists to perform the due diligence and valuation processes. A full proof valuation would require accurate and appropriate information as gathered during the due diligence exercise. Additionally, the acquirer should satisfy themselves on the accuracy of the following: In our previous paper on intrinsic value in mergers and acquisitions, we indicated that there are numerous valuation methods which can e employed. These methodologies may be applied to determine the company valuation range and include: The determination of the method to be applied depends on the size of the target, the industry in which it operates, the line of business and whether or not it is listed. The technical mechanics are for another paper. Suffice to say that the following factors affect valuation: The conclusion of the evaluation stage leads into the execution stage which requires that the following considerations be made. # Consideration Description 1 Acquisition vehicle Shelf Company Holding Company Partnership Joint Venture (JV) Trust 2 Post-closing Full integration Subsidiary Shared ownership/ control 3 Form of payment Cash Debt (LBO & MBO) Real Estate Share Swop Phased/ Deferred Contingent 4 Legal form of selling entity Limited Liability Company or Partnership | Ordinary shares, Preference Shares | Convertible Preference Shares [#, %ge, Type, Debt Financing] 5 Form of acquisition Cash or debt for assets Cash or debt for equity Shares for shares Shares for assets Merger (vertical or horizontal) 6 Tax considerations Impact on Shareholders or the Business (NewCo and OldCo) 7 Accounting (Pre & Post) Reporting Earnings Valuations The ultimate objective for performing due diligence and valuation work is to reduce risk to manageable or acceptable levels for purposes of deal negotiation and consummating a business relationship post-M&A. When the acquirer performs risk assessments pre-negotiation, the should consider the following: Finally, go to the negotiating table! Clive Munemo CA(Z)Clive Munemo is a Chartered Accountant and the Managing Consultant for Clive and Associates which is a boutique advisory firm located in Harare. He is a leading business consultant working with both the public and private sector corporations in Zimbabwe and in the region. He has vast experience in audit, tax, advisory and consulting. www.cliveandassociates.com

M&A Action and Intrinsic Value
Zimbabwe is abuzz with words of optimism following the events of November 2017 which led to a change in leadership in the country. While this may be the case, and investment opportunities may be beckoning, companies need to be well structured and ready to receive investment from equity investors.
